
Military retirement seems simple on the surface.
You serve your time, you retire, and you receive a pension.
But for many veterans, that expectation changes the moment VA disability compensation enters the picture. What should be two separate benefits suddenly becomes a confusing system of offsets, rules, and exceptions that are rarely explained clearly.
That’s where most frustration begins.
Many retirees find themselves asking:
- Why is my military retirement pay lower than expected?
- Am I allowed to receive both retirement and disability?
- Is the VA taking part of my pension?
- What exactly is “concurrent receipt”?
Understanding the answers to these questions is critical if you want a clear picture of your long-term retirement income.
The Core Issue: The VA Disability Offset
At the center of the confusion is something called the VA disability offset.
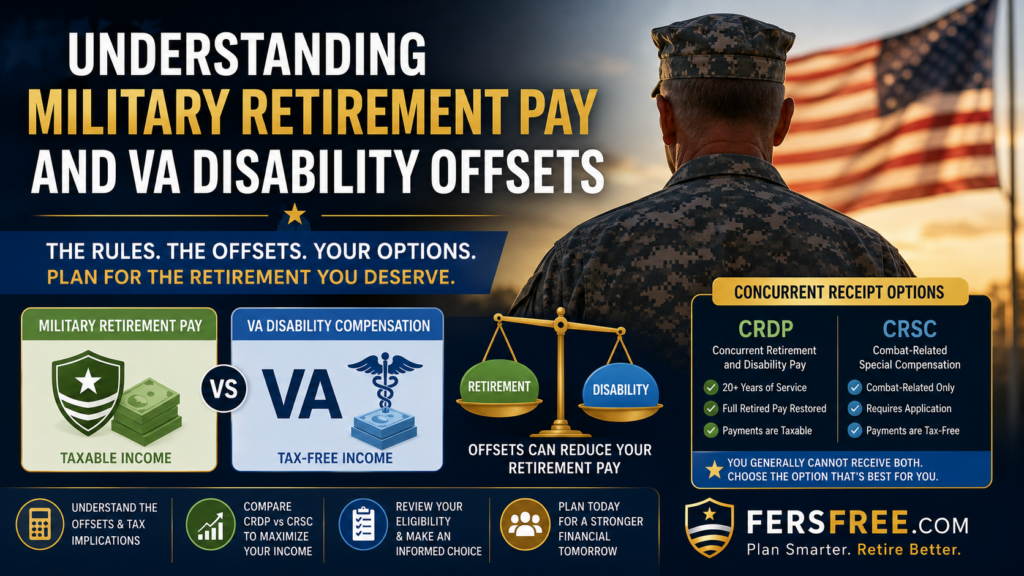
Historically, federal law did not allow veterans to receive full military retirement pay and full VA disability compensation at the same time. Instead, retirees were required to waive a portion of their retirement pay equal to their VA disability amount.
In practical terms, that means:
- You receive VA disability compensation (tax-free)
- Your military retirement pay is reduced by a similar amount
So while your total income may not drop significantly, the structure of that income changes—and that has real financial consequences.
Why This Feels Wrong to Veterans
From a policy standpoint, the government treats VA disability as a replacement for income lost due to service-connected conditions.
But many veterans see it differently.
From their perspective:
- Retirement pay is earned through years of service
- Disability compensation is for injury or sacrifice
- One should not reduce the other
That disagreement is exactly why this issue has remained controversial for decades and continues to drive reform efforts today.
The Hidden Factor: Taxes
One detail that often gets overlooked is taxation.
Military retirement pay is generally:
- Taxable
VA disability compensation is:
- Tax-free
So when part of your retirement pay is replaced by VA disability, your taxable income decreases.
That means the offset isn’t always a pure loss—it can reduce your tax burden. But without understanding this, many veterans assume they are simply losing money.
Concurrent Receipt: The Partial Solution
To address these concerns, Congress introduced programs that allow certain retirees to receive both payments with reduced or eliminated offsets.
This is known as concurrent receipt.
There are two main programs:
- CRDP (Concurrent Retirement and Disability Pay)
- CRSC (Combat-Related Special Compensation)
Each works differently, and choosing between them can significantly impact your finances.
CRDP: Restoring Your Retirement Pay
CRDP allows eligible retirees to receive:
- Full military retirement pay
- Full VA disability compensation
Key details:
- Typically requires 20+ years of service
- Applies to qualifying disability ratings
- Payments are still taxable
For many retirees, CRDP effectively restores income that was previously reduced by the offset.
CRSC: A Different Option for Combat-Related Disabilities
CRSC is designed specifically for veterans with combat-related disabilities.
Key characteristics:
- Requires application and approval
- Payments are tax-free
- Only applies to qualifying combat-related conditions
Because CRSC is tax-free, it can sometimes produce better net income than CRDP depending on your situation.
CRDP vs CRSC: Choosing Matters
Many veterans don’t realize they may need to choose between these two options.
You generally cannot receive both at the same time.
The better option depends on:
- Your disability type
- Your tax situation
- Your overall retirement income
This is one of the most overlooked financial decisions in military retirement.
Chapter 61 Retirees Face the Most Complexity
If you were medically retired (Chapter 61), your situation may be even more complicated.
You may encounter:
- Partial offsets
- Limited access to concurrent receipt
- Unique calculation rules
This group is often at the center of ongoing legislative reform discussions because the system affects them more heavily.
Why This Matters Long-Term
This is not just a technical issue—it directly affects your financial future.
The interaction between retirement pay and VA disability impacts:
- Monthly income
- Tax liability
- Retirement sustainability
- Survivor benefits
Over a 20–30 year retirement, even small monthly differences can add up to a significant amount of money.
Common Mistakes Veterans Make
Many veterans unintentionally make planning mistakes such as:
- Assuming both benefits are always paid in full
- Not understanding how the offset works
- Ignoring tax implications
- Choosing CRDP or CRSC without comparison
- Never modeling long-term retirement income
These mistakes can lead to inaccurate expectations and poor financial decisions.
The Bigger Picture
Military retirement is not just about your pension.
It is about how multiple income sources work together:
- Military retirement pay
- VA disability compensation
- Civilian retirement (if applicable)
- Social Security
- Healthcare benefits
When these are not evaluated together, retirement planning becomes fragmented and confusing.
Key Takeaway
Military retirement pay and VA disability compensation do not always work the way veterans expect.
The offset, concurrent receipt programs, and tax implications all play a role in determining what you actually receive.
Understanding these interactions is essential if you want a clear and confident retirement plan.
What to Do Next
If you are a veteran or military retiree, take time to review your full retirement income picture:
Compare:
- Total monthly income
- Taxable vs tax-free income
- Eligibility for CRDP or CRSC
- Long-term sustainability
Disclaimer
This article is for educational purposes only. Military retirement and VA disability rules are complex and may change. Always verify your situation with DFAS, the VA, or a qualified professional.